
Tandem Bank Review 2026: Is This Savings-Only Bank Worth It?
Choosing the right bank can be tricky with so many digital options. When you hear that Tandem Bank isn’t actually a current account, you might wonder if it’s even worth considering. But for many, the competitive savings rates and unique “green” focus are more than enough to change their minds.
Here is the updated review for 2026.

Tandem review
The Tandem account is very basic. And I mean very. However, the savings rates are incredibly competitive, so it’s worth considering if you have some money to put away.
Pros
- Great interest rates
- Choose between fixed and instant-access
- Connect other bank accounts for an overview
Cons
- Borrowing costs can be expensive
- Not much else available from Tandem
 Reviewed by Household Money Saving
What is Tandem Bank?
Tandem Bank is a UK-based digital bank that concentrates on savings, mortgages and environmentally focused lending. Unlike Monzo or Starling, there is no current account. You won’t be switching your salary here or paying bills from it.
The “fairer, greener” angle isn’t just branding. Deposits are used to fund things like solar panels, air-source heat pumps and home insulation projects across the UK.
Tandem was founded in 2013 and acquired Harrods Bank in 2018, which gave it a full UK banking licence. That matters, because it means your money is protected by the FSCS up to £85,000, just like any high-street bank.
Is Tandem Bank safe?
Yes. Tandem is fully authorised in the UK and FSCS protection covers eligible deposits up to £85,000 per person. If Tandem went bust, your money would be protected within those limits. There’s no extra risk here compared to any other regulated savings provider.

Tandem Bank savings rates (2026)
This is where Tandem earns its reputation. It quietly sits near the top of the “best buy” tables far more often than people realise.
Instant Access Saver
Rate: 3.40% AER
This includes a 0.25% “Top Up” bonus for the first 12 months.
Access: Unlimited withdrawals, no penalties, money available 24/7.
This account is simple, flexible and competitive. It’s the sort of account I use as a holding pot for emergency savings or money I don’t want locked away.
Also worth reading
If you want to switch to a digital bank, take a look at this Monzo review as a decent alternative.
Instant Access Cash ISA
Rate: 4.00% AER (variable)
Access: Full flexibility with tax-free interest.
If you’ve already used your Personal Savings Allowance elsewhere, this is one of the stronger easy-access ISAs around right now.
Fixed savings and fixed ISAs
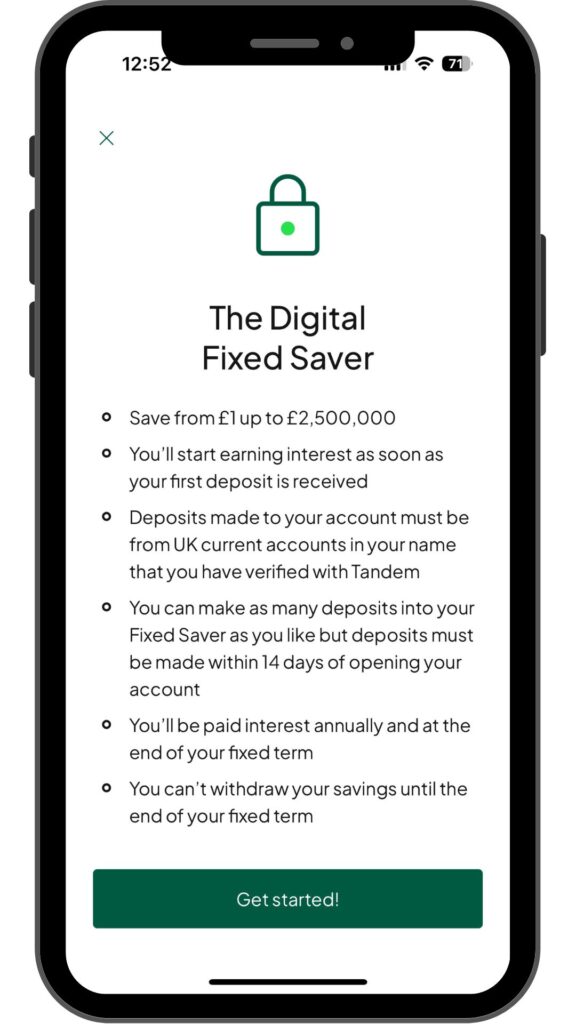
If you’re willing to lock your money away, Tandem’s fixed rates are usually even more appealing.
1-year fixed saver: 4.28% AER
Fixed-rate Cash ISA: up to 4.20% AER depending on term
They’re rarely the absolute top of the table, but they’re consistently competitive without nasty catches.
Key features worth knowing
Portfolio ISA
This is one of Tandem’s smarter ideas. It lets you split your £20,000 ISA allowance across instant access and fixed-rate pots, all within one ISA wrapper. For people who like to ladder savings without opening multiple accounts, this is genuinely useful.
Green lending
Tandem is officially a “Purpose-Led” bank. Your deposits help fund energy-efficient home improvements, not generic consumer credit. If you care where your money ends up, this is a real differentiator rather than a gimmick.
Open Banking
You can link external bank accounts to see balances in one place. It’s handy, but basic. Don’t expect deep spending analysis or budgeting tools like you’d get from Monzo or Starling.
What happened to Tandem’s old features?
If you remember Tandem from a few years back, a lot has changed.
Round-ups were removed in 2023. If you want spare-change saving, you’ll need something like Plum or Moneybox alongside Tandem.
The cashback credit card was discontinued in 2021. There’s no replacement, and it’s clear Tandem isn’t interested in competing in the rewards space anymore.
Mortgages are still very much part of the business, particularly green mortgages. Homeowners with high EPC ratings can get preferential rates, which fits neatly with Tandem’s wider ethos.
Also worth reading
If you’re looking for a new bank, take a look at the best cashback and reward accounts.
Final thoughts: is Tandem Bank worth it in 2026?
Tandem Bank is not an everyday bank, and it never will be. If you want a single app to run your entire financial life, this isn’t it.
But if you want a no-nonsense place for your savings, with consistently strong interest rates and a genuinely green focus, Tandem does exactly what it says on the tin. The app is stable, clean and refreshingly boring in a good way.
For me, Tandem works best as a “quiet workhorse” savings bank sitting alongside a main current account elsewhere. It doesn’t shout. It doesn’t bribe you with freebies. It just pays decent interest and stays out of the way.
That’s often exactly what you want.
If my Tandem review has you interested in finance apps, why not take a look at my review of the best budgeting and personal finance apps.
Tandem Bank FAQs
Is Tandem Bank safe?
Yes. Tandem Bank is fully authorised in the UK and your eligible deposits are protected by the FSCS up to £120,000. It holds a full banking licence (via its acquisition of Harrods Bank), so it’s no riskier than a high-street bank.
Is Tandem Bank a current account?
No. Tandem does not offer a current account. There’s no debit card for spending, no bill payments, and no overdraft. It’s a savings-first bank designed to sit alongside your main current account.
What savings accounts does Tandem offer?
Tandem offers instant access savings, fixed-rate savings, Cash ISAs (both instant access and fixed), and a Portfolio ISA that lets you mix easy access and fixed savings under one ISA allowance.
Are Tandem’s interest rates competitive?
Yes. Tandem consistently sits near the top of the UK best-buy tables for both easy-access savings and fixed rates. While it’s not always number one, the rates are strong and stable without gimmicks.
What is the Tandem ‘Top Up’ bonus?
Some savings accounts include a temporary bonus (currently 0.25%) for the first 12 months. After that period ends, the rate drops to the underlying variable rate, so it’s worth diarising a review date.
Can I withdraw money instantly?
Yes, from instant access savings and ISAs. Withdrawals are unlimited and penalty-free, with funds available 24/7.
Does Tandem offer a credit card or cashback?
No. Tandem discontinued its cashback credit card in 2021 and removed round-up features in 2023. If you want cashback or spending rewards, you’ll need a separate bank or card.


