Are Premium Bonds Worth It Or A Waste Of Money?
Are Premium Bonds worth it? Or are they just a clever way of making savers feel like they’re investing when they’re not?
I’ll be honest — I used to love the idea of them.
Growing up, my family were big fans. I remember those brown envelopes arriving telling my parents they’d won £25 or £50. It felt exciting. Safe. Sensible. Almost clever.
So when I started getting serious about my own finances, Premium Bonds were one of the first places I looked.
But the more I dug into the numbers, the less impressed I became.
Here’s the reality in 2026 — and why I still don’t invest in them.
What Are Premium Bonds?
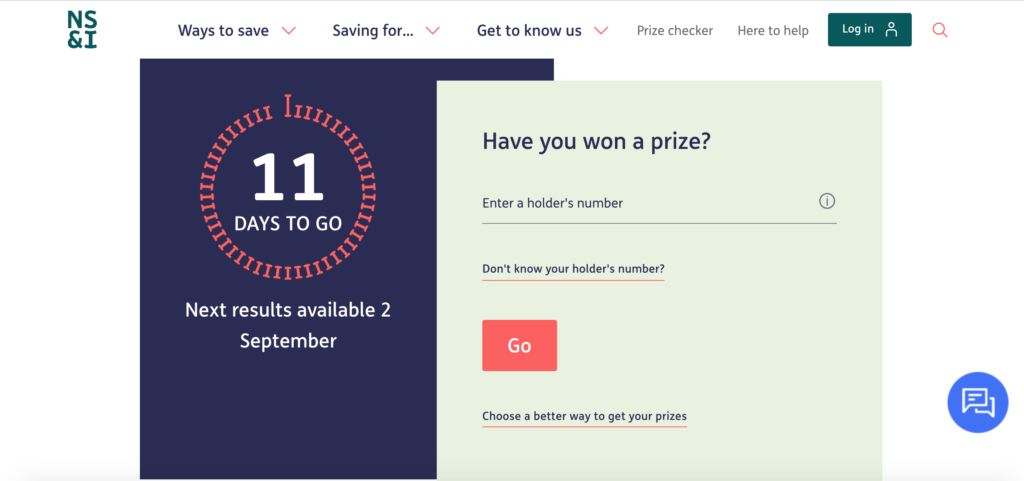
Premium Bonds are issued by National Savings & Investments (NS&I).
Instead of earning interest, your money is entered into a monthly prize draw. Every £1 bond gives you one chance to win. Prizes range from £25 to £1 million.
Your capital is fully backed by the UK Government. You can withdraw your money at any time. But there is no guaranteed return.
It’s effectively savings with a lottery element attached.
How Much Do Premium Bonds Cost?
Each bond costs £1.
Minimum investment: £25
Maximum holding: £50,000 per person
So £10,000 gives you 10,000 chances in every monthly draw.
The more you hold, the more chances you have.
But more chances doesn’t mean predictable returns.
Are Premium Bonds Safe?
Yes — completely.
They’re backed by the UK Government via NS&I, so your full holding (up to £50,000) is protected.
If safety is your only goal, they tick the box.
The real question isn’t safety.
It’s whether they’re worth it.
The 2026 Numbers You Need To Know
As of February 2026:
• Prize fund rate: 3.60%
• Odds of each £1 bond winning: 1 in 22,000 per month
• Two £1 million prizes paid every month
That 3.60% figure is important.
It’s not a personal interest rate.
It’s the total prize pot divided across all money invested in Premium Bonds.
And that’s where things get misunderstood.
Why Most People Earn Less Than 3.6%
Because the prize fund is skewed by the two £1 million jackpots (and other high-value prizes), the average is pulled up by a small number of big wins.
If you hold around £10,000 and have “normal” luck, you’re statistically more likely to earn closer to 3.0%–3.2%, not 3.6%.
Some people win more.
Some people win nothing.
That unpredictability is what made me uncomfortable.
Also worth reading
If you enjoy the excitement, why not take a look at other savings accounts offering prizes?
What If You Invest £10,000?
At a 3.60% prize fund rate, you might expect around £360 per year on average.
But realistically, with typical luck, it could be nearer £300–£320.
Or you could win £0.
There’s no steady compounding. No guaranteed monthly interest. Just draws.
That’s fine if you enjoy the excitement.
It’s less appealing if you’re trying to build wealth methodically.
The Opportunity Cost
Here’s the bit that really changed my view.
Let’s say you have £50,000.
A top easy-access savings account paying 4.5% would earn you £2,250 guaranteed over a year.
With Premium Bonds at 3.6%, the statistically likely outcome is around £1,600.
That’s roughly £650 per year you’re giving up for the small chance of a life-changing win.
When I framed it like that, the decision became obvious.
I don’t want to “pay” hundreds a year for excitement.
The Inflation Trap
Inflation is projected at roughly 2.5% for 2026.
If you have a bad-luck year and win nothing, your money has effectively lost 2.5% of its purchasing power while sitting there “safely”.
Even at a 3% return, you’re only just keeping pace.
That’s not growth.
That’s standing still.
Premium Bonds Vs The Alternatives
Here’s how they stack up right now:
Product | “Return” | Risk | Tax |
|---|---|---|---|
Premium Bonds | 3.60% prize rate (not guaranteed) | Zero capital risk | Always tax-free |
Easy-access savings | ~4.50% (top rates) | Zero capital risk | Taxable above allowance |
Inflation (CPI) | ~2.5% | N/A | Reduces value |
Premium Bonds sit in a strange middle ground.
Safe like savings.
Returns like a raffle.
Who Are Premium Bonds Actually Worth It For?
To be fair, they do have a niche.
They make the most sense for:
• Higher-rate (40%) taxpayers who’ve used their £500 Personal Savings Allowance
• Additional-rate (45%) taxpayers with no allowance
• People who have already maxed out their ISA allowance
• Anyone holding a large emergency fund who values safety over growth
If you’re a higher-rate taxpayer, a 4.5% savings account becomes 2.7% after 40% tax.
Suddenly, a 3.6% tax-free prize rate looks more competitive.
But for basic-rate taxpayers who haven’t used their allowance?
The maths usually favours savings accounts.
So, Are Premium Bonds A Good Investment?
In my opinion — no, not as a long-term wealth-building tool.
Here’s why I don’t use them:
• Returns are luck-based
• Most people earn less than the headline rate
• Inflation quietly erodes value
• Strong savings accounts often pay more
• Long-term investing historically offers better growth (with risk)
I’d rather earn a guaranteed 4–5% on cash and invest the rest for long-term compounding.
The brown-envelope excitement is real.
But the maths of compounding usually beats the maths of excitement.
Where I Put My Money Instead
For short-term cash, I use competitive savings accounts when rates are strong.
For long-term growth, I invest through a Stocks & Shares ISA with Fidelity.
Historically, broad market investing has delivered higher long-term returns than cash products — although values go down as well as up.
I also use a Lifetime ISA, where the government adds a 25% bonus on contributions (up to £4,000 per year). That’s a guaranteed uplift Premium Bonds simply can’t compete with.
Investing carries risk.
But at least the returns are based on growth — not luck.
The Honest Verdict
Premium Bonds are:
Safe ✔
Tax-free ✔
Easy access ✔
Guaranteed growth ✖
Reliable income ✖
Inflation-proof ✖
If you want a safe place to park money with a small chance of a big win, they’re fine.
If you’re serious about building wealth over decades, there are usually better options.
That’s why I still don’t own any — even though I grew up thinking they were the smart choice.
FAQ: Are Premium Bonds Worth It?
Are premium bonds worth it in 2026?
They can be worth it for safety and tax efficiency, particularly for higher-rate taxpayers. But they’re unlikely to outperform top savings accounts or long-term investing.
Are premium bonds safe in the UK?
Yes. They’re fully backed by the UK Government through NS&I.
Do most people win 3.6%?
No. The 3.6% is a prize fund rate across all holders. Many individual savers earn less.
Is it better to save or buy premium bonds?
If you can get a higher guaranteed interest rate and stay within your tax allowance, savings accounts usually win.