Zopa Biscuit Account Review 2026: 7.10% Saver, Cashback & £10 Bonus
The Zopa Biscuit account (officially launched in summer 2025) is Zopa Bank’s first step into everyday banking, and it’s deliberately not trying to replace your main current account.
Instead, Biscuit is built as a high-yield “satellite” account. The idea is simple: use it for bills and savings-adjacent cash, earn interest on money that would otherwise do nothing, and unlock some of the best rates inside the Zopa app, all without paying a monthly fee.
It won’t suit everyone. Cashback is capped, switching support is still limited, and it’s app-only. But if you’re happy running a second account and moving money around strategically, Biscuit punches well above its weight.
New customers can also earn a £10 welcome bonus by opening the account using a referral link, which is an easy win on top of the ongoing interest and cashback.
Below is a breakdown of how the Zopa Biscuit account stacks up in 2026.

Zopa Biscuit review
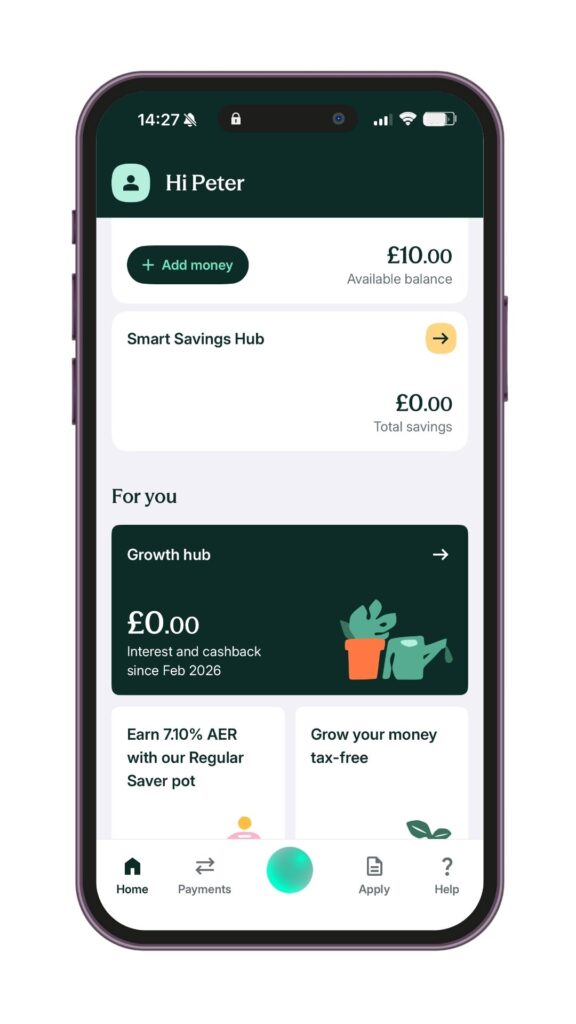
The Zopa Biscuit account is a game-changer for savers. It is one of the few free current accounts to offer interest on your daily balance alongside bill cashback. Its biggest draw, however, is the exclusive access to a 7.10% Regular Saver, making it an essential “hub” for anyone looking to maximise their interest in 2026.
Pros
- Market-leading 7.10% AER Regular Saver pot
- 2% AER interest on your main account balance
- 2% cashback on Direct Debits (capped at £30/year)
- No fees for spending your money abroad
Cons
- The £30 annual cashback limit is quite low
- No branches for depositing physical cash or cheques
- Overseas ATM withdrawals are capped at £200 fee-free
- You have to manage everything via the mobile app
 Reviewed by Household Money Saving
Feature | Details |
|---|---|
Monthly Fee | £0 |
In-Credit Interest | 2.00% AER (Fixed for 12 months) |
Cashback | 2% on Direct Debits (Capped at £30/year) |
Linked Regular Saver | 7.10% AER (Save up to £300/month) |
Overseas Spending | Fee-free (Visa exchange rate) |
Atm Withdrawals | Fee-free up to £200/month (2% fee thereafter) |
Key benefits
1. The “Dough”: interest and cashback
Zopa markets Biscuit as an account that pays you to use it, and within its limits, that’s true.
Credit interest
Earning 2.00% AER on a free current account is rare. You can beat it with specialist easy-access savings accounts, but Biscuit is ideal for money that sits around temporarily: bill money, emergency buffers, or cash waiting to be moved elsewhere.
Direct Debit cashback
You earn 2% cashback on up to £1,500 of Direct Debits per year, a maximum of £30 annually. Unlike Santander Edge, this cashback isn’t limited to specific “essential” bills. Almost any Direct Debit counts, which makes it easier to hit the cap without micromanaging your payments.
Also worth reading
Not convinced by Zopa? Check out the best reward current accounts in the UK
2. The 7.10% Regular Saver
This is the real reason most people should open a Biscuit account.
Biscuit customers get exclusive access to a 7.10% AER Regular Saver, allowing deposits of up to £300 per month. Crucially, Zopa lets you withdraw and replace money within the same month without losing your interest rate, something many competitors don’t allow.
Used properly, this pot alone can outperform the interest earned from the current account and cashback combined.
3. The 4.75% Easy-Access “Boost”
As of late 2025, Zopa also introduced an exclusive 4.75% AER easy-access rate for Biscuit customers.
To unlock it, you’ll typically need to deposit at least £500 per month into your Biscuit account. This is a very competitive rate, compared to your average high street bank.
The drawbacks
No full CASS support (yet)
As of early 2026, Zopa doesn’t always support the full Current Account Switch Service. If you want to move Direct Debits across to earn cashback, you may need to do it manually.
Capped cashback
The £30 annual cashback limit is easy to hit, but it’s still low. If your household bills are very high, a paid account like Santander Edge could work out better overall.
Digital-only banking
There are no branches. If you regularly deposit cash or cheques, Biscuit won’t work as your primary bank.
ATM limits abroad
You get £200 per month of fee-free overseas withdrawals. That’s tighter than competitors like Starling Bank, which offers fee-free withdrawals up to a £300 daily cap.
Using Biscuit to build credit (with a big caveat)
Zopa also nudges Biscuit users towards its “Borrowing Power” tools, which show personalised loan and credit card eligibility without a hard search. Used carefully, this can help with credit building, but it’s not cheap credit.
Representative rates are high (around 22.9% APR on loans and 34.9% APR on cards), so this is not borrowing you’d want to carry long-term. However, for someone with a thin or improving credit file, taking a small amount of credit, using it lightly, and repaying in full and on time can help demonstrate good behaviour to lenders.
The key point: this only makes sense if you never pay interest. If you’re tempted to carry a balance, skip this entirely; the savings and cashback are where Biscuit really shines.
Who is this for?
The Zopa Biscuit account is a no-brainer for existing Zopa savers who want to unlock higher rates with minimal effort.
It’s also an excellent option for “strikers”, people who like to move money around to capture the best interest rates, as there’s no hard credit check to open the account and no monthly fee to justify.
Pro Tip: Pair the Biscuit account with a Chase debit card. Use Biscuit for your Direct Debits (to get the 2% bill cashback) and use Chase for your supermarket spending (to get their 2% debit card cashback).
How much can you realistically earn with the Zopa Biscuit account?
Let’s assume a fairly typical setup.
You use the Zopa Bank Biscuit account to pay household bills, keep a modest cash buffer, and make regular savings contributions.
- Average current account balance: £2,000
At 2.00% AER, that earns roughly £40 per year in interest. - Direct Debit cashback:
If your household bills total at least £1,500 per year, you’ll hit the cap and earn the full £30 annually. - Referral bonus (new customers):
Open the account using a referral link and you’ll receive a £10 one-off bonus.
That’s £80 in the first year before factoring in any savings interest.
Now add the real kicker:
- Regular Saver:
If you save the full £300 per month into the 7.10% AER Regular Saver, you’ll earn around £140–£150 in interest over 12 months, depending on how consistently you fund it.
Total realistic return in year one
- Current account interest: £40
- Cashback: £30
- Referral bonus: £10
- Regular Saver interest: £145
Total: roughly £225 in the first year
That’s not life-changing money, but for a free, low-effort secondary account, it’s about as good as it gets in 2026.
A Direct Debit cashback tip
If you don’t want to wait ages to earn your £30 from your Direct Debits, there’s a quicker way to do it.
If you have a Plum account, link it to Zopa. Then head to the “Brain” section and choose “Pay Days”. Select the saving amount as £1,500 and choose a date suitable for you. Once the money reaches Plum, you can send it back to your bank. An easy £30.
If you’re not a customer, find out more from my Plum review or download the Plum app for free.
Verdict
The Zopa Biscuit account is a “tasty” (see what I’ve done there?) addition to the UK banking market. The cashback cap is modest, and it won’t replace a traditional current account, but that’s not what it’s trying to do.
When used as a secondary account, the combination of in-credit interest, Direct Debit cashback, a market-leading Regular Saver, and a £10 referral bonus makes it one of the best “extra” accounts you can own in 2026.
If you’re prepared to use it strategically, Biscuit more than earns its place in your wallet.
Zopa Biscuit account FAQs
Is the Zopa Biscuit account free?
Yes. There’s no monthly fee and no minimum balance requirement. You only pay if you exceed certain limits, such as overseas ATM withdrawals above £200 per month.
Can I use the Zopa Biscuit account as my main bank account?
You can, but it’s not ideal. Biscuit works best as a secondary or “satellite” account for bills and savings, rather than a full replacement for a high-street current account.
How does the 2% Direct Debit cashback work?
You earn 2% cashback on up to £1,500 of Direct Debits per year, capped at £30 annually. Most Direct Debits qualify, not just essential bills.
Is the 7.10% Regular Saver easy to access?
Yes. You can save up to £300 per month, and Zopa allows you to withdraw and replace money within the same month without losing the interest rate.
Does Zopa Biscuit support the Current Account Switch Service?
Not fully. As of 2026, you may need to move Direct Debits manually if switching from another bank.
Can I earn a bonus for joining?
Yes. New customers can earn a £10 bonus by opening a Zopa Biscuit account using a referral link.
Is my money safe with Zopa?
Yes. Zopa is a UK-regulated bank, and eligible deposits are protected up to £120,000 under the Financial Services Compensation Scheme.