Better Off, Better You Part 2: Cutting Your Outgoings
In part one, we discussed looking through our finances to see how much money we had coming in and going out of our accounts each month. And now that you know exactly how your finances look, it’s time to improve them. By that, I mean cutting costs.
I know that people are often a little cautious when trying to save money because they think it means cutting out things they enjoy. But that’s often not the case. Even by changing a supplier or negotiating a new deal, you could save yourself a few pounds per month in just a few minutes. Do this with several suppliers and you could be £20-£30 better off each month without losing anything.
Where to start
Your first stop should be looking through your bank statement to see if you’re paying for anything you no longer use. Research shows that collectively, we waste £300m on subscriptions and hobbies in which we no longer have an interest. I’m not sure whether this is because we forget about them or we plan to use them again one day. But take a look and see if you’re still paying for something you aren’t using.
This is also a good chance to see if there are any direct debits set up that you don’t recognise. And using internet banking, you can cancel any direct debit at the touch of a button. But be careful. Companies can use different names when taking payments and you don’t want to cancel something you actually need. A quick Google search should tell you whether you need to keep a direct debit.
Once done, we can move on to the next step.
Consider cancelling anything unnecessary
I know I said that this wasn’t about cancelling things you enjoy but have a good think about what you really need. For example, I know people who not only subscribe to Sky but also have Netflix, Amazon Prime and Disney+. Now, I’m sure there are programmes on each of these channels that we can all enjoy. But are there enough hours in the day to watch them all and will you get value for money?
Why not subscribe for one month, binge-watch, and then cancel? It could save you over £70 per year.
Finding better deals
Now that you’ve scrapped anything you don’t want or need, it’s time to look at your remaining bills, negotiate a better deal, or even switch providers.
You see, most companies rely on their customers not having the time to switch or look for a better deal and hope that they automatically allow their contracts to renew.
It might seem a little daunting at first if you’ve never tried negotiating before. But companies are used to it and are generally keen to keep you as a customer. In most cases, it shouldn’t take you much more than 15 minutes to sort out each of your bills.
Some companies will allow you to speak to them over live chat on the internet, but in most cases, you will need to phone. You should set aside a couple of hours and try to get through as many companies as possible.
But which to tackle first?
Usually, my first recommendation would be to switch energy providers. This can often save people as much as £800 per year. But the end of 2021 has thrown a spanner in the works and the advice is not to switch. This will change over time, but we’ll just ignore it.
Mortgage or rent – this is the most significant bill for the majority of households. Unfortunately, if you rent your home, there’s little you can do to negotiate a better deal. With housing stock in relatively short supply, landlords usually hold the upper hand.
But mortgage holders may be able to reduce their monthly payments. If you haven’t switched deals for several years, there’s a good chance that you may be on your lender’s standard variable rate (SVR). This can often be 1-2% higher than a fixed or discounted rate. On a £150,000 mortgage, switching deals could save as much as £250 per month.
Switching deals with your current mortgage provider is much simpler than most would believe. As long as your circumstances haven’t changed since taking out your initial deal, it shouldn’t take long. In fact, some banks allow you to do it online with the push of a button and you’re accepted within seconds.
If not, give your provider a ring or pop into your local branch to discuss what can be done.
Broadband and internet – ensuring you have the right broadband package isn’t always the easiest thing to figure out. Do you know the difference between megabits per second (Mbps) and kilobits per second (Kbps)?
And to confuse matters further, there are two types of internet connection – broadband and full-fibre. Broadband generally uses older wiring in your house, with full-fibre using fibre-optic cables to your home, giving you far faster speeds.
The fact is, internet speed is increasing all of the time. And although that’s great if you love watching films in UltraHD or have a family of 5 that play online simultaneously, these super speeds aren’t necessary for everybody. If you’re a small household and only need basic internet, you certainly don’t need an all singing all dancing internet service.
No matter which service is right for you, if you’re out of contract, it should be easy to find a better deal. You can either give your current provider a ring to see what they can do for you or you can check for offers on a price comparison site.
But your best bet is usually to take out a new contract through a cashback site like TopCashback. You can earn anything between £30 and £150 back by clicking a link. So not only will your monthly price be cheaper, you should also get a lump sum back.
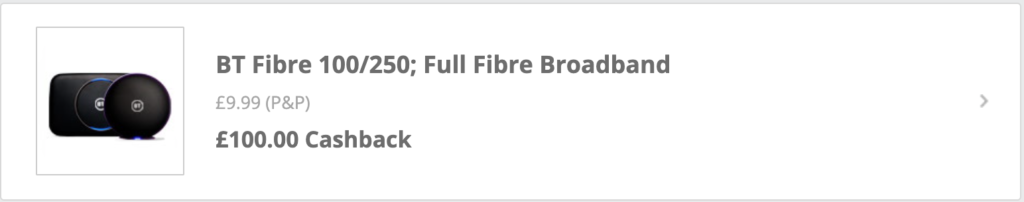
If you’ve never used one before, look at how cashback sites work.
Mobile phone – this is another bill that people tend to overlook. Let’s be honest, we often get sucked into getting a new phone when our old contract expires. And buying a new phone and contract often means we’re paying over the odds.
But once that contract has expired, you can look for a SIM-only deal that should cost you far less. See some comparison sites like uSwitch to see what’s on offer. For most users, there’s no reason they should be paying more than £10 per month. If you see a better deal, contact your current provider to see if they will match it. If they won’t play ball, then you can switch. It’s very simple and you won’t need to change your number. In fact, you can do it just by sending a simple text.
Insurance – insurance companies are no different from any other on this list and they hope that you don’t bother to shop around. And if you don’t look elsewhere, you’re probably paying too much.
But there is some good news. A change in legislation meant that from the 1st of January 2022, insurance companies have to offer the same prices to both old and new customers. That means that if you allow your policy to renew, you should get a decent(ish) price. But this change doesn’t necessarily mean you’re getting the best deal.
Look at a comparison site for home insurance to see if they can beat your current price. Many of us use our bank for home cover, but they often offer poor value. In most cases, you can cancel a home insurance policy midway through a contract and receive a partial refund without a penalty. But check with your provider before you do.
Car insurance is another policy where you can save a lot of money by switching. And again, you can usually cancel a policy early and receive a refund. But think carefully before you do this. If you’re building up your no-claims bonus, you won’t get a whole extra year if you cancel before the end. You must make sure that the saving is substantial if you switch partway through.
Sky TV – with over 12 million customers in the UK, I thought it was important to touch on Sky TV. With some packages costing more than £100 per month, you must ensure you’re getting a good price. Now, you can drop channels from your package, but you do have to lose quite a few before it makes a dent in your bill.
Negotiating with Sky is the best way I have found to save money. A 30-minute chat can give you as much as 50% off your bill each year without losing any of your favourite channels. I know 30 minutes sounds like quite an effort, but remember, it could save you £100’s each year. You can do this online or over the phone. And in some cases, you may even find that you’ll have an offer in your Sky account.
Take a look at my guide to negotiating with Sky.
Childcare
My final tip for saving money is to cut childcare costs. Hopefully, you should know that if you have young children, you’re entitled to a certain number of free childcare hours each week. This is meant to give you more free time so you can work more.
However, if that isn’t enough or your children are a little older, you qualify for tax-free childcare. You can get up to £500 every three months (up to £2,000 a year) for each of your children to help with childcare costs. This goes up to £1,000 every three months if a child is disabled (up to £4,000 annually).
All you need to do is set up an online childcare account and for every £8 you pay into this account, the government will pay in £2 to use to pay your provider.
Using any or all of the above should go some way to reducing your monthly outgoings.
In part 3, we’ll examine how changing your lifestyle could save you even more money.